Bank Manager Mocked Black Man for “Wasting Time” — Then Learned He Was Their Billion-Dollar Invest
Bank Manager Mocked Black Man for “Wasting Time” — Then Learned He Was Their Billion-Dollar Invest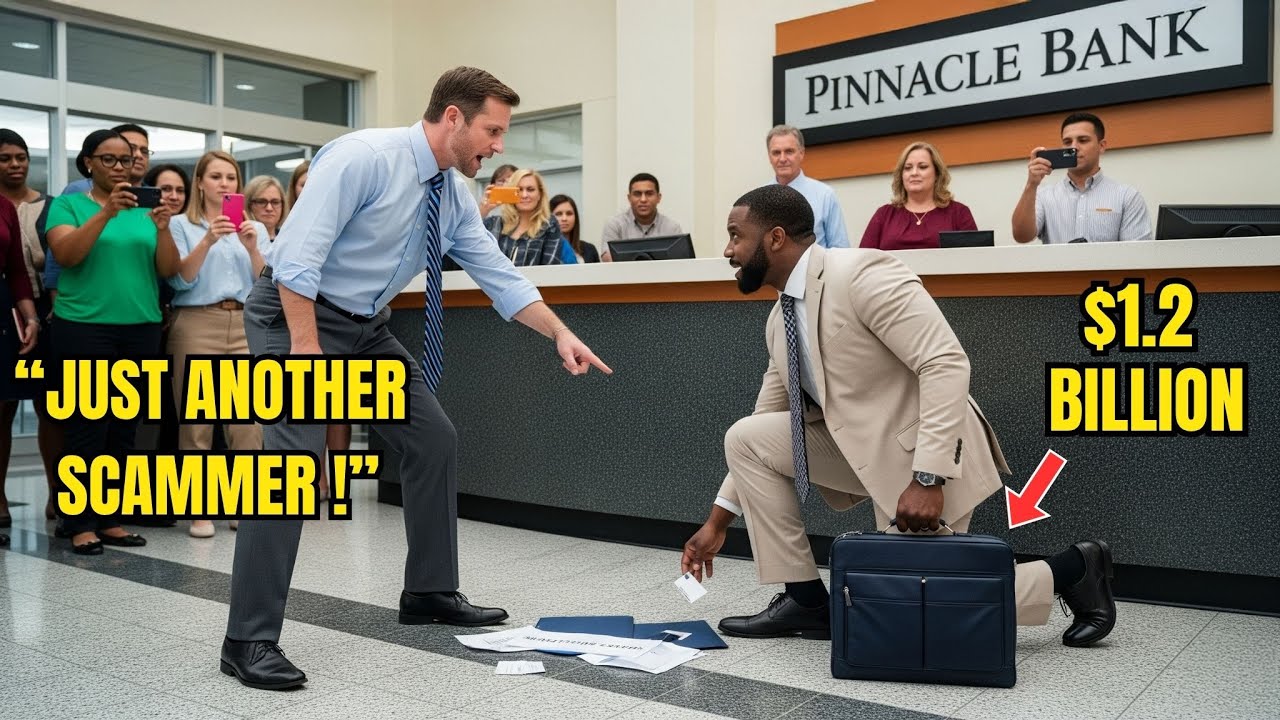
Thomas Weber’s finger jabs towards a well-dressed black man. You people always waste time. There are real customers waiting. The crowded Pinnacle Bank lobby falls silent. Bank manager Thomas Weber approaches Dr. Alexander Coleman, deliberately knocking the leather portfolio from his hands. Premium business cards and investment documents scatter across the floor.
If you have a real appointment, where’s your proof? Weber demands loudly. Coleman kneels to gather his belongings, maintaining his dignity despite the public humiliation. “Security, keep an eye on him,” Weber calls, gesturing to a guard who immediately steps closer. “Sir, I need to verify your identity,” the guard states firmly.
Coleman stands jaw tight with controlled anger as customers stare. He produces his ID, which Weber barely glances at before dismissing it. Anyone can get fake identification these days. Coleman’s expression hardens as he reaches for his phone and types a message. Time to activate plan B. They have no idea who they’re dealing with. Little does the manager know, Doctor Coleman isn’t just any customer.
He’s about to become the bank’s majority investor. Dr. Alexander Coleman arrives at Pinnacle Financials flagship branch in downtown Chicago at precisely 9:15 a.m. His charcoal suit is tailored to perfection, his Oxfords polished to a mirror shine. Yet, he keeps his appearance intentionally understated. No flashy watch, no designer labels on display.
His portfolio contains documents for a scheduled meeting about potentially investing $1.2 billion from his medical technology venture fund into the bank’s new digital division. The branch bustles with morning activity. Thomas Weber, the 52-year-old branch manager, paces behind the teller line, his face flushed with stress. Three staff called in sick.
The lines stretch toward the door and the regional director visits tomorrow. His collar feels tight around his neck. Coleman approaches the reception desk with a polite smile. Good morning. I have a 9:30 appointment with the investment division. Dr. Alexander Coleman. The receptionist, Diane, new to the position, searches her computer.
I’m sorry, sir. I don’t see any appointment under that name. Weber overhearing immediately steps over. He gives Coleman a quick once over, his eyes narrowing slightly. Is there a problem here? I have an appointment with the investment division, Coleman explains calmly. It may be under Coleman Ventures rather than my name.
Vber doesn’t check the system. Everyone has an appointment when they want to skip the line. You’ll need to wait like everyone else. I understand you’re busy, but this is a scheduled meeting regarding a significant investment opportunity. Sure it is, Vber says with a dismissive wave. Take a seat. We’ll get to you when we get to you.
For the next hour, Coleman observes Vber’s behavior from a hard plastic chair in the waiting area. When an older white couple enters, Weber personally greets them. Mr. and Mrs. Davidson, let me help you right away. When a young white professional mentions he’s in a hurry, Weber finds him immediate assistance. Meanwhile, Coleman’s polite attempts to follow up are repeatedly rebuffed.
As Coleman waits, now 2 hours past his appointment time, his phone lights up with the pinnacle CEO’s name, completely unaware his billiondoll investor is being treated like an unwelcome intruder. After 3 hours of waiting, Coleman approaches the desk again. The lobby has cleared somewhat, yet no one has called his name.
His patience wears thin, but his expression remains neutral as he addresses Weber directly. Excuse me. I’ve been waiting for nearly 3 hours now, and I’m significantly late for my appointment upstairs. Weber doesn’t look up from his computer. His fingers continue to tap at the keyboard as he responds. Everyone has to wait their turn.
Your time isn’t more valuable than anyone else’s. He pauses, then adds with a pointed edge. You people always think your time matters more than others. The words hang in the air. A nearby customer looks uncomfortable, quickly averting her gaze. Coleman’s voice remains level. I’d like to speak with another manager, please. Vber finally looks up, his eyes moving deliberately over Coleman’s suit, his clean shaven face, his professional demeanor. seeing none of it.
I am the highest authority present today. If you’re unhappy with our service, perhaps you should try the community bank down the street. Might be more, he pauses. Your kind of place. The implication is unmistakable. Coleman’s jaw tightens almost imperceptibly. Meanwhile, 14 floors above them, the investment division grows increasingly concerned.
Franklin Pierce, Pinnacle’s CEO, checks his watch again. This isn’t like Dr. Coleman. He’s never late for meetings. Sarah Chen, VP of acquisitions, ends another call attempt. Still going straight to voicemail. This doesn’t make sense. His team confirmed yesterday. This is a $1.2 billion opportunity we can’t afford to lose, Pierce says, pacing.
especially with the acquisition rumors circulating. Coleman’s investment could keep us independent. Back in the lobby, Coleman stands his ground. I have an appointment regarding a significant investment opportunity with your bank. I’ve been more than patient. Vber laughs, the sound sharp and dismissive. Sure you do. Listen, if you don’t have actual banking business to conduct, I’ll have to ask you to leave. We serve real customers here.
Coleman’s phone vibrates in his pocket. Another call from upstairs that he doesn’t answer. His expression hardens just slightly. I see. And what exactly does a real customer look like to you, Mr. Weber? Weber’s name tag suddenly feels prominent on his chest. He hadn’t introduced himself. Upstairs, the investment team finally calls down to the branch floor, asking if anyone has seen Dr.
Alexander Coleman, their billion-dollar meeting that could save the bank from acquisition. The desk phone rings sharply. Weber snatches it up, his eyes never leaving Coleman’s face. Pinnacle branch manager Weber speaking. He listens for a moment, his expression shifting subtly. One moment, please. He puts the call on hold, the blinking light pulsing like a warning.
So, Wayabber says, his voice taking on a dangerous edge. You’re claiming to be Dr. Coleman, the one they’re expecting upstairs. I am Dr. Alexander Coleman, he responds, reaching for his wallet. Of course you are. Weber’s tone drips with sarcasm. He raises his voice deliberately, ensuring nearby customers and staff hear every word.
And I’m the Federal Reserve chairman. Coleman produces his driver’s license, sliding it across the counter. My identification. Weber barely glances at it. Anyone can get fake IDs these days. Pretty sophisticated scam you’re running. He pushes the license back. Trying to impersonate someone with money to access restricted areas of the bank.
The accusation hangs in the air. Several customers turn to stare. Coleman feels their eyes on him, judging, questioning, assuming. The weight of these stairs is familiar, a burden he’s carried his entire professional life. This is absurd, Coleman says, his voice tight with controlled anger. Call upstairs and verify my identity.
Oh, I’m sure your accomplice would verify whatever you want. Vber gestures to a security guard. I believe this individual is attempting to commit fraud by impersonating a client. An older white customer steps forward. This is completely unprofessional. You haven’t even properly checked his credentials. Wayber dismisses her with a wave.
Ma’am, I’m handling a security situation. Please step back. The blinking hold light continues its rhythmic pulse. Upstairs, executives grow impatient with being left on hold. Sarah Chen, frustrated by the lack of response from the branch floor, grabs her tablet. I’m going down there myself. Something isn’t right.
Back in the lobby, Weber steps around the counter, invading Coleman’s personal space. Empty your pockets, please. Let’s see what else you’re carrying. Absolutely not. Coleman stands his ground. I will not be humiliated further. That’s what I thought. You have no right to be here. Vber’s voice rises again. Either comply or leave the premises immediately.
The elevator doors open and Sarah Chen emerges into the lobby, her eyes scanning for her missing investor. She spots the confrontation immediately, the gathering crowd, the security guard approaching, and Coleman standing rigidly as Weber continues his tirade. She rushes forward. Dr. Coleman. Weber turns. Ma’am, please step back.
This individual is the neurosurgeon and venture capitalist our entire executive team has been waiting for all morning. Chen finishes, her face flushing with embarrassment. Dr. Coleman, I am so deeply sorry. What is happening here? Labour’s face drains of color, but his posture remains defensive. There was a misunderstanding.
We have security protocols that that apparently include racial profiling and public humiliation. Coleman interrupts, his voice quiet but carrying. He turns to Chen. I apologize, Miss Chen, but I won’t be staying for the meeting. I need to reconsider certain aspects of our potential partnership.
Chen’s expression falls. Dr. Coleman, please. Whatever happened, I’m sure we can. What happened is quite clear to everyone present. Coleman buttons his suit jacket. Good day. He walks toward the exit, his back straight, his dignity intact despite everything. Through the glass doors, a black Mercedes idles at the curb, his driver watching the scene unfold with concern.
As Coleman leaves, he makes a call to his assistant. Contact our legal team and the SEC and set up a meeting with Pinnacle’s board of directors, but don’t tell them why. The Mercedes pulls away from the curb, merging smoothly into downtown traffic. Only now, in the privacy of the back seat, does Coleman’s composed facade crack.
His hands tremble slightly as he loosens his tie. He takes one deep breath, then another, struggling to process the humiliation he just endured. “You all right, Doc?” his driver, Michael, asks, meeting Coleman’s eyes in the rearview mirror. “I saw what happened through the windows. That man had no right. Coleman stares out at the Chicago skyline.
30 years, Michael, medical school at Hopkins, neurosurgery fellowship at Mayo, built a tech company worth billions, and still, his voice trails off, still treated like you don’t belong. Michael finishes quietly. Exactly. Coleman straightens his shoulders. But this is the last time from this institution.
The very last time. He reaches for his phone, scrolling past the 15 missed calls from Pinnacle’s executive team. Instead, he dials his chief financial adviser. Janet, assemble the team for an emergency meeting in 30 minutes. Full digital attendance, highest security protocols. He pauses. It’s time to execute project watershed, but with modifications.
At Pinnacle’s headquarters, chaos erupts. Sarah Chen bursts into the conference room where the executive team waits anxiously. He’s gone. He left. Her voice shakes slightly. There was an incident downstairs with manager Weber. Dr. Coleman was treated. She searches for an appropriate word. Abhorrently. CEO Franklin Pierce stands abruptly.
What exactly happened? From what I gathered, he was made to wait for hours accused of fraud. nearly had security called on him and was told to empty his pockets to prove he belonged there. “Dear God,” Pice whispers. “The $1.2 billion investment is likely gone,” Chen finishes. “And frankly, sir, that should be our secondary concern right now.
The way he was treated.” Pierce is already dialing his phone. “Get Weber on video conference now.” His face reens as he waits. This is a disaster. Vber appears on screen, his expression defensive before anyone speaks. What the hell happened down there? Pierce demands. There was a misunderstanding. Wayber begins.
This individual didn’t properly identify himself as an important client. He looked like he was trying to skip the line, claiming to have some big appointment. So, you automatically assumed he was lying. Based on what exactly? Vber shifts uncomfortably. Sir, we have procedures. He didn’t fit the profile of our typical high- netw worth clients.
If he’d just explained who he was more clearly. Stop talking. Pierce cuts him off. You’ve said more than enough. In Coleman’s downtown office, his team assembles virtually and in person. Financial advisers, legal counsel, investment strategists, all waiting as Coleman outlines his plan. Our original strategy was straightforward.
A direct investment in Pinnacle’s digital banking division. That’s off the table now. He brings up a display showing Pinnacle’s stock ownership structure. Instead, we’re executing a three-phase plan. Phase one, quiet acquisition of shares through our various holdings companies. I want significant ownership without triggering disclosure requirements as long as possible.
His general counsel raises a concern. And what’s the endgame here, Alex? Revenge. Coleman shakes his head firmly. Not revenge. Reform. Phase two will be a comprehensive investigation into discriminatory practices at Pinnacle. Not just regarding me, but systemically. And phase three, he pauses, looking at each team member.
Phase three is where we use our leverage to create meaningful change in their corporate culture and practices. His chief investment officer nods slowly. We have the capital to acquire up to 30% without excessive market disruption if we move carefully. Then let’s begin immediately. Coleman’s expression is resolute. What happened today wasn’t about me.
It’s about every person who walks into that bank without a billion dollars behind their name and faces the same treatment or worse. That stops now. As Coleman finalizes his plans, Pinnacle’s CEO receives an alert that someone is rapidly purchasing significant blocks of the bank’s stock, but they can’t identify the buyer.
One week passes. Coleman’s investment team works with Precision, acquiring Pinnacle shares through seven different holding companies. Their ownership now stands at 12%, significant, yet still below the threshold requiring public disclosure. The bank’s stock price rises slightly on the increased trading volume, but no one at Pinnacle has connected these purchases to Coleman.
Meanwhile, Coleman meets with Ramirez Investigations in a discrete corner office overlooking Lake Michigan. Their lead investigator slides a preliminary report across the table. “We’ve documented 28 instances of discriminatory practices across Pinnacle’s Chicago branches in just one week,” she explains.
“Varying wait times, different document requirements, inconsistent lending standards based on customer demographics.” Coleman reviews the data. This confirms what I suspected. It’s not isolated to one branch or one manager. Later that afternoon, Coleman sits across from Gabrielle Torres, a civil rights attorney with an impressive record of victories against financial institutions.
Her office walls display framed settlements from three major banks. The evidence you’re gathering is compelling, Torres says, reviewing the investigative reports. But to create lasting change, we need to demonstrate this is systemic, not anecdotal. Coleman nods. That’s precisely my goal. I don’t just want Weber held accountable.
I want to transform how the entire institution operates. You could simply take your business elsewhere, Torres points out. Most people in your position would nothing would change, Coleman replies. The next person who walks in looking like me but without my resources would face the exact same treatment. At Pinnacle’s downtown branch, Weber gathers his staff for a morning meeting.
His formal reprimand sits in his personnel file, but his position remains secure, a fact that hasn’t escaped notice among the employees. “We need to be extra vigilant about security protocols,” Weber tells his team, his tone clipped. “Certain individuals may be looking to create situations they can leverage against the bank.
Be respectful but firm with all customers who don’t follow proper procedures.” A new teller raises her hand. What exactly does that mean? It means use your judgment, Weber replies with a meaningful look. And be particularly careful with customers who might be looking to cause trouble. Several staff members exchange glances, understanding the coded language.
In his office, CEO Franklin Pierce reviews the latest attempts to contact Coleman. All calls go unanswered. All emails receive the same automated response. Dr. Coleman is re-evaluating his relationship with Pinnacle Financial. “We need to fix this,” Pierce tells Sarah Chen. “The PR exposure alone could be devastating if this gets out.” Chen hesitates.
“With all due respect, sir, perhaps we should be focusing on fixing the actual problem rather than just the perception.” Pierce waves dismissively. “Of course, of course, but damage control comes first. Find a way to get Coleman back to the table.” What neither of them realizes is that Coleman now receives notifications of their board calls as a significant shareholder.
He listens to PICE’s concerns about image rather than substance, confirming exactly what he suspected about the corporate culture. Coleman receives a report showing Weber has a history of similar incidents that Pinnacle has systematically buried and the whistleblower is someone inside the bank. Coleman’s ownership stake in Pinnacle Financial reaches 23% by the third week of his quiet acquisition campaign.
The bank’s leadership notices the unusual stock movement, creating ripples of concern through the executive ranks. During an emergency call, board members speculate wildly about who might be behind the purchases. Could be Meridian trying a hostile takeover, suggests one director. or foreign investors looking for a foothold in American banking.
Whoever it is, they’re being deliberate about staying just under the disclosure threshold, PICE observes, tension evident in his voice. I don’t like it. Across town, Coleman waits in a quiet coffee shop several blocks from Pinnacle’s main branch. He checks his watch. 3:15 p.m. Exactly. As a young woman in business casual attire approaches his table.
She glances nervously over her shoulder before sitting down. Dr. Coleman, I’m Diane. We met briefly at the branch. Recognition flickers in Coleman’s eyes. The receptionist. Thank you for coming. She places a USB drive on the table, sliding it toward him with trembling fingers. Everything’s here. Seven discrimination complaints against Weber in 5 years.
All settled with NDAs and cash payments. Coleman doesn’t touch the drive yet. Why are you doing this? You’re risking your job. Diane’s eyes harden. My grandmother couldn’t get a home loan from Pinnacle in 1983 despite perfect credit. My mother couldn’t in 2001. I thought things had changed when they hired me. They haven’t.
She takes a deep breath. There’s more. Weber has blocked promotion recommendations for every minority employee in his branch. The documentation’s all there. Performance reviews altered, qualifications questioned, always with plausible deniability. Coleman nods, finally taking the drive. I’ll ensure you’re protected.
I don’t want protection, Diane replies firmly. I want change. Meanwhile, Vber grows increasingly paranoid. He notices unfamiliar customers lingering longer than usual, observing interactions throughout the branch. What he doesn’t realize is their investigators documenting the differential treatment of clients based on race and appearance.
Wayber calls an impromptu staff meeting. Effective immediately, we’re implementing enhanced security protocols. Any non-rine transactions require secondary ID verification. He pauses, lowering his voice. Use discretion in application, but be thorough with high-risk profiles. A veteran teller frowns. What constitutes high risk? You know exactly what I mean. Weber snaps.
Don’t make me spell it out. By weeks end, customer complaints increase 40%. Most come from minority clients subjected to enhanced verification for routine transactions. Regional management takes notice, requesting an explanation for the sudden spike. At Pinnacle Headquarters, Sarah Chen spends her evening researching Dr. Alexander Coleman, digging deeper than the standard executive profile.
What she uncovers is staggering. His medical patents, tech investments, philanthropic work, and influence throughout multiple industries. more concerning connections to several holding companies that have recently purchased Pinnacle Stock. She stares at her screen, connecting dots that no one else has. After a long moment, she closes her laptop without sharing her discovery.
Her loyalty to the institution waivers as she weighs what she’s learned against what she witnessed in the branch that day. The bank’s board calls an emergency meeting about the anonymous stock purchases, and Coleman receives his official invitation as a major shareholder who can no longer remain anonymous.
Coleman reviews the formal invitation to Pinnacle’s emergency board meeting scheduled for 9:00 a.m. tomorrow. His legal team surrounds him in his office’s conference room, finalizing strategy for the revelation that can no longer be delayed. They’ve discovered your ownership position, his general counsel explains. SEC regulations require your attendance as a major shareholder.
Coleman nods, studying the proposed agenda. Perfect timing. Our investigation has gathered enough evidence to support comprehensive demands for change. His lead attorney slides a document across the table. These are our non-negotiable terms for reform. Legal has vetted them for enforcability and PR has shaped them for maximum impact.
Coleman reviews the list. Independent audit of all discrimination complaints over the past decade. Mandatory antibbias training with measurable outcomes. Executive diversity overhaul. Community accountability board with actual authority. Transparent lending criteria applied equally across demographics. And if they resist, Coleman asks, “Then we go public with everything,” his communications director responds.
“The investigation findings, the whistleblower documents, the pattern of settlements, their stock would plummet, and regulatory agencies would launch immediate investigations.” Coleman taps the document thoughtfully. Make it clear. We prefer cooperation, but we’re fully prepared for confrontation. At Pinnacle Headquarters, the executive team prepares for battle against their mysterious shareholder.
CEO Franklin Pierce stands before a whiteboard covered with defensive strategies. We need to present a united front, he insists. Whoever this investor is, they’re clearly positioning for a hostile action. Our priority is protecting shareholder value and maintaining independence. Board members nod in agreement, none aware of the true identity of their new major investor.
Only Sarah Chen sits quietly, conflicted by her suspicions and her loyalty to the institution. What if this isn’t an attack? She finally ventures. What if it’s an opportunity? Pierce scoffs. An opportunity? Anonymous stock accumulation is never friendly, Sarah. This is finance 101. Maybe we don’t know the full picture, she persists, carefully avoiding revealing her suspicions.
We’ll know tomorrow, PICE concludes, dismissing her concerns. Until then, we stand firm against any demands that compromise our operational autonomy. Across town, Coleman meets with a coalition of community banking advocates and civil rights leaders in a private dining room. He shares his plans while servers place dinner before the influential group.
What you’re attempting is unprecedented, says Reverend Michaels, a respected voice in economic justice. Most people with your resources would simply invest elsewhere. Walking away would be easier, Coleman acknowledges. But creating systemic change requires working from a position of power. I have that power now. The question is, will you stand with me publicly when the time comes.
The community leaders exchange glances, then one by one, they nod their agreement. This isn’t just about one incident or one bank, Coleman continues. It’s about changing the fundamental ways financial institutions interact with communities of color. Success here creates a template we can apply throughout the industry.
Meanwhile, Weber attempts damage control, sensing his position weakening. He approaches employees individually, seeking statements supporting his management style. Most comply out of fear, but resistance grows, especially after Dian’s quiet advocacy among her colleagues. Morning arrives.
Coleman adjusts his tie before stepping into his waiting car. Today’s suit is different. Midnight blue, impeccably tailored with subtle gold cuff links bearing his family crest. No more understated appearance. Today he displays his power openly. Ready, Doc? Michael asks, holding the car door. More than ready, Coleman replies.
It’s time they understand exactly who they’re dealing with. As Coleman enters Pinnacle’s headquarters for the board meeting, he walks past Weber in the lobby, who fails to recognize him and once again asks if he has an appointment. Pinnacle Financials executive boardroom buzzes with tense energy. 12 board members arrange themselves around the polished mahogany table, whispering strategies and concerns.
CEO Franklin Pierce paces at the head, reviewing notes for his defensive presentation. The bank’s chief legal council sits alert, prepared for confrontation with their mysterious investor. “Any word on who we’re dealing with?” a board member asks Pierce. “None. Their attorneys have been frustratingly discreet,” Pice responds, checking his watch.
“But we’re prepared for any reasonable or unreasonable demands.” Sarah Chen sits quietly, watching the door, her suspicions unshared. At precisely 9:00 a.m., the boardroom door opens. Coleman strides in, flanked by his legal team. The room falls silent. Several executives who were present during the original investment meeting instantly recognize him, their expressions shifting from confusion to horrified realization.
Pierce, who has never met Coleman in person, steps forward with a practiced smile. Welcome. I’m Franklin Pierce, CEO of Pinnacle Financial, and you are Dr. Alexander Coleman. His voice carries easily across the room. Though we were scheduled to meet 3 weeks ago regarding a $1.2 billion investment in your digital banking division.
PICE freezes, the color draining from his face. Chen closes her eyes briefly, her suspicions confirmed. Dr. Coleman. Pice recovers quickly. There seems to have been a misunderstanding. If we could discuss that unfortunate incident privately. There was no misunderstanding, Coleman interrupts calmly.
And nothing about this discussion will be private. He gestures to his team. I’m here today in my capacity as the owner of 23% of Pinnacle Financials outstanding shares. The announcement lands like a physical blow. Board members exchange alarmed glances as Coleman takes a seat at the table directly opposite PICE. You’re the one who’s been purchasing our stock, Pierce states unnecessarily.
Yes. Coleman opens his briefcase, removing a thick bound report which he places deliberately on the table. And now we need to discuss why. Coleman’s lead attorney distributes copies of the report to each board member. This contains documented evidence of systematic discriminatory practices throughout Pinnacle’s branches, specifically targeting customers of color.
These are serious allegations, the bank’s council begins. These are facts, Coleman corrects, gathered by independent investigators over the past 3 weeks, supplemented by internal documents provided by your own employees. Board members frantically flip through the report, expressions growing increasingly grim. Pierce attempts to regain control.
Dr. Coleman, while we take any allegation of impropriety seriously, I’m sure we can come to an arrangement that satisfies your concerns without drastic measures. Perhaps a private settlement. I’m not here for a settlement, Coleman interrupts, his voice hardening. I’m not here for revenge or to damage this institution. I’m here to fix it.
He stands, commanding the room’s complete attention. Let me be clear about my position. I have the capital to increase my ownership to a controlling interest. I have evidence that could trigger regulatory investigations and class action lawsuits. But what I want is reform. Coleman outlines his demands one by one.
The independent audit, the antibbias training, the executive diversity overhaul, the community accountability board, and transparent lending criteria. The board splinters in its reactions. Some members appear calculating, assessing the financial implications. Others seem genuinely shocked by the evidence presented.
A few look openly hostile to Coleman’s demands. Sarah Chen raises her hand. I’ve reviewed the evidence and I support Dr. Coleman’s proposals. All eyes turned to her in surprise. What happened to him? What’s apparently happening to many customers goes against everything this institution should stand for. PICE glares at her, but she continues, “We have an opportunity to lead the industry in meaningful reform rather than being dragged into it through public scandal.
” Coleman nods appreciatively at Chen before addressing the entire board again. “What you experienced from me today, walking in with power you didn’t know I possessed, happens to people like me every day in reverse. We walk into spaces where our worth, our character, our very humanity is instantly undervalued based on appearance.
He pauses, letting the words sink in. I could afford to walk away. Most people facing discrimination in your branches can’t. They need these banking services, these loans, these opportunities, and they deserve equal treatment regardless of their net worth. Pierce, recognizing the precarious position of the bank, shifts to damage control.
Dr. Coleman, your points are well taken. We’re prepared to consider your proposals, but such significant changes require time and careful implementation. Perhaps we could form a committee to study. No committees, no studies, no delays. Coleman’s tone brooks no argument. you implement these changes immediately and transparently.
And if we require confidentiality around this arrangement, PICE asks, to protect the bank’s reputation during transition, Coleman’s expression hardens. Transparency is non-negotiable. The problems occurred in public. The solutions will be public as well. The tension in the room is palpable as PICE realizes he has no leverage.
Coleman owns enough shares to force a board vote that Pierce would likely lose. The evidence in the report could trigger regulatory action. The bank’s stock would plummet if this became public without a clear remediation plan. We’ll need to discuss the specifics. Pierce concedes reluctantly. Of course, Coleman agrees.
My team will work with yours on implementation, but the board votes on these principles today. Now, as the board prepares to vote, Coleman delivers his final point. One more thing. I’ve scheduled a press conference for 9:00 a.m. tomorrow morning. Either Pinnacle announces these reforms alongside me, demonstrating its commitment to change, or I announce my findings independently.
The choice is yours. As the board meeting concludes with a reluctant vote in favor of Coleman’s demands, his phone silently receives text confirmation that his team has just completed acquiring another 4% of Pinnacle’s shares. Insurance against any lastminute resistance. The hours following the board meeting erupt in controlled chaos across Pinnacle Financial.
Emergency strategy sessions fill conference rooms. Legal teams draft compliance frameworks. HR executives review personnel policies. The PR department crafts crisis messaging. In the executive suite, Pierce paces before his leadership team. This is the most significant transformation in Pinnacle’s history, and we have less than 24 hours to prepare for a public announcement.
It’s the right thing to do, Sarah Chen interjects, earning glares from several colleagues. Right or not, it’s happening. Pierce snaps. I need implementation plans from every department by midnight. Across town, Coleman briefs his coalition of civil rights leaders and community banking advocates.
Pinnacle’s board has approved all our demands. Tomorrow, we announce the partnership publicly. Partnership? Reverend Michaels questions. That’s generous terminology for what you’ve orchestrated. Coleman shakes his head. This isn’t a hostile takeover. It’s a transformation. The distinction matters if we want lasting change rather than defensive compliance.
At 9:00 a.m., Coleman takes the podium, flanked by Pierce and board members on one side, civil rights leaders on the other. Their uncomfortable alliance shows in their rigid postures. Today marks a new chapter for Pinnacle Financial and potentially for the banking industry as a whole, Coleman begins.
Pinnacle is announcing comprehensive reforms to ensure equitable banking practices for all customers regardless of race, ethnicity, or economic background. He outlines each initiative. The independent audit of discrimination complaints, mandatory antibbias training with measurable outcomes, executive diversity overhaul, community accountability board, transparent lending criteria.
These changes represent not just words, but actionable, measurable commitments with real consequences for non-compliance, Coleman explains. Pierce steps forward, his statement, careful, but committed. Pinnacle Financial acknowledges that we have not always lived up to our values of equal service to all customers.
Today, we commit to systemic change. Across town, Thomas Weber watches the press conference, his face contorting in disbelief. The man he humiliated now controls the bank’s future. He fumbles for his phone, dialing Pierce’s direct line. The call goes unanswered. Instead, his desk phone rings. Human Resources. Mr.
Weber, your presence is requested in a meeting regarding your employment status, effective immediately. The press conference continues with reporters questioning Coleman and Pierce. “Dr. Coleman, was your stock acquisition motivated by personal discrimination at Pinnacle?” asks a Wall Street Journal reporter. “My investment decisions are always based on potential value,” Coleman responds.
In this case, I recognize that Pinnacle could become more valuable by serving all communities equally. CEO Pierce, “Will there be accountability for employees who engaged in discriminatory practices?” challenges a reporter from Black Enterprise magazine. Pierce shifts uncomfortably. “We’re conducting a thorough review of all personnel.
Appropriate actions will be taken based on findings. The story explodes across media within hours. Financial news leads with the unprecedented reforms. Civil rights organizations praise the concrete accountability measures. Banking industry analysts debate the potential impact on Pinnacle’s bottom line. By afternoon, three other major banks announce proactive reviews of their own practices, attempting to get ahead of potential scrutiny.
At Pinnacle headquarters, implementation begins immediately. Coleman’s diversity consultants arrive to begin the audit process. HR distributes new customer interaction guidelines. Legal reviews all NDA settlements from the past decade. Diane receives a call from Sarah Chen. The board has approved your promotion to diversity and inclusion coordinator for your branch.
Effective immediately. What about Weber? Diane asks cautiously. Suspended pending investigation, Chen confirms. And between us, he won’t be returning. Weber sits with his personal attorney reviewing options. They can’t make me the scapegoat for institutional practices, he fumes. His attorney looks skeptical.
The evidence suggests you applied protocols disproportionately based on race. That’s difficult to defend. It’s a witch hunt, Weber insists. I’m filing a wrongful termination suit against both Coleman and Pinnacle. Meanwhile, Coleman meets with his legal team. Weber is threatening litigation. His council reports claims he’s being scapegoed. Let him, Coleman responds.
Discovery will only strengthen our position on systemic issues. One week later, the initial audit results arrive, confirming widespread disparities in service, loan approvals, and wait times based on customer demographics across multiple branches. The findings trigger regulatory interest from both the Federal Reserve and the Consumer Financial Protection Bureau.
Investment analysts issue mixed recommendations on Pinnacle stock. Some predict short-term volatility but long-term growth from expanded market share in previously underserved communities. Others express concern about compliance costs. Coleman addresses these concerns on financial networks. Banking institutions that view equitable service as a burden rather than an opportunity are missing the point.
There’s untapped market potential in communities that have been historically underbanked. Throughout the financial industry, executives hold emergency meetings. Compliance officers revive diversity initiatives previously treated as checkbox exercises. HR departments review complaint histories for patterns previously ignored.
Sarah Chen presents the first month’s progress to the board. The changes are creating positive ripples beyond expectations. Customer satisfaction scores have increased 27% across all demographics in reformed branches. As reforms begin taking shape, Weber makes a desperate move, filing a defamation lawsuit against both Coleman and Pinnacle, forcing a public hearing that could expose even more of the bank’s dirty laundry.
The Cook County Courthouse buzzes with media activity as Thomas Weber climbs the steps in his new suit. His attorney whispers lastminute advice. Remember, you’re the victim of corporate scapegoating, not personal bias. Inside, Coleman sits calmly beside his legal team as Judge Morrison calls the preliminary hearing to order.
The gallery overflows with journalists and activists. This hearing will determine if there are grounds for Mr. Weber’s defamation claims, she explains. Weber’s attorney approaches with confidence. Your honor, my client has been made the fall guy for institutional practices. Pinnacle Financial colluding with Dr. Coleman has destroyed Mr.
Weber’s reputation to protect their corporate image. Coleman’s attorney counters, “This lawsuit attempts to reframe discriminatory behavior as policy. Mr. Weber applied protocols selectively based on race. Furthermore, defamation requires false statements. Everything said about Mr. Weber was demonstrably true.
Under cross-examination, Weber’s facade crumbles rapidly. “Why did you require Dr. Coleman to empty his pockets when white customers conducting similar transactions weren’t asked to do so?” Coleman’s attorney asks. “He was exhibiting suspicious behavior,” Weber claims. “What specific behaviors were suspicious?” “He was insistent about an appointment we couldn’t verify.
Yet you personally assisted three white customers who arrived after him. Were you too busy for them as well? When presented with data showing desperate treatment patterns, Weber grows defensive. Different customers require different approaches. It’s about risk management. Risk based on what criteria exactly.
Weber hesitates too long. Experience. Professional judgment. Diane’s testimony delivers precision strikes with her documented evidence, specific incidents, language used, and service discrepancies based solely on appearance. Mr. Weber instructed us to apply enhanced verification to certain customers, she explains.
When asked for clarification, he would say things like, you know, the type. But the pattern was clear. Minority customers faced additional scrutiny regardless of their transaction type. The fatal blow comes during redirect examination when Weber’s own attorney attempts damage control. Would you have treated Dr. Coleman differently had you known his financial status? Weber responds, “Of course.
That’s just good business. High-V value clients receive premium service.” Coleman’s attorney pounces, “So you admit that you prejudge people’s value based on appearance alone, then treat them accordingly? That’s not what I Weber stops, realizing his admission. Judge Morrison dismisses the defamation claims and refers the case to the Civil Rights Division for potential further action.
Outside, reporters surround Weber as protesters hold signs reading, “Banking while black shouldn’t be a crime.” His prepared statement evaporates as cameras thrust toward him. I was just doing my job, he begins, then stops, seeing the hostility his words generate. I I may have misjudged the situation. That evening, Coleman meets Weber in a neutral conference room.
The formerly confident manager enters cautiously. “I never thought of myself as prejudiced,” Weber says. “I was just doing what I thought was best for the bank.” “That’s the problem,” Coleman responds evenly. You equated best for the bank with excluding people who looked like me. That equivalence is the definition of systemic racism.
Coleman slides a folder across the table containing resources for bias education and community organizations. I’m not offering forgiveness, Mr. Weber. I’m offering an opportunity to become part of the solution rather than continuing to be part of the problem. Weber stares at the folder before taking it.
Why would you do this after what I did to you? This was never about you or me, Coleman replies. It’s about changing a system that damages everyone it touches, including you. As news of Weber’s complete downfall spreads through the financial industry, Coleman receives calls from leaders at five other major banks, nervously asking for meetings.
6 months later, Pinnacle Financial’s flagship branch displays a new sign. Community Banking Center, equal service, equal opportunity. Inside, both customers and staff reflect Chicago’s diverse population, a visible transformation from before. After initial volatility, Pinnacle stock now trades 17% higher than pre-reform levels.
Their inclusive policies have attracted previously alienated customers with major investment firms upgrading Pinnacle to strong buy status, citing expanded market reach as a competitive advantage. Coleman chairs the ethics and inclusion board, reviewing progress with community leaders and financial experts. Our audit identified 342 cases of potential discrimination over the past decade.
We’ve contacted each affected customer with appropriate remediation. More importantly, our metrics now show consistent treatment across all demographic groups. Sarah Chen, now executive vice president of community banking, reports measurable impacts from antibbias training. Customer satisfaction scores have equalized across demographics and loan approval rates now correlate solely with financial qualifications.
Coleman leverages this success with regulatory agencies. testifying before the Federal Reserve Banking Committee. His advocacy leads to new standards requiring banks to report demographic data on service times, loan approvals, and complaints, metrics previously hidden from public view. Other institutions respond with varying sincerity.
Some implement genuine reforms recognizing the business opportunity in properly serving diverse communities. Others make performative changes without substantive policy shifts. Coleman’s media appearances specifically highlight authentic reforms while critiquing diversity theater, creating market pressure for meaningful change.
The Financial Services Equity Coalition transforms the industry through mystery shopper testing for discriminatory practices with quarterly published results. Banks scoring poorly face regulatory scrutiny and public backlash. In previously underserved communities, the impact materializes economically. Small business loan approvals in predominantly black and Hispanic neighborhoods increase 64% industrywide.
Mortgage approvals rise 42%. The wealthbuilding tools of traditional banking begin reaching communities long excluded. At a financial conference, Coleman presents the business case for equitable banking. This isn’t charity. It’s sound strategy. Institutions authentically embracing these reforms are capturing market share and customer loyalty that will benefit their bottom line for decades.
As he concludes, Coleman notices Thomas Weber in the audience, representing urban financial literacy project, a nonprofit focused on economic justice in minority communities. As Coleman presents these industry changes at a financial conference, he spots a familiar face in the audience, Weber, now working for a nonprofit focused on economic justice in minority communities.
One year after the initial confrontation, Coleman returns to Pinnacle’s flagship branch. The physical space has been redesigned. Gone are the imposing teller counters and security glass that created barriers between staff and customers. In their place stand open service desks arranged to facilitate conversation rather than emphasize authority.
Diane, now the branch manager, greets him warmly. Her confident posture and executive suit reflect her rapid rise within the organization. Advancement based on merit finally recognized. Dr. Coleman, welcome back. It’s always good to see you. Her handshake is firm, professional, colleague to colleague rather than subordinate to power.
The changes look substantial, Coleman observes, noting the diverse customer base being served with equal attention and respect. More than cosmetic, Diane confirms, guiding him through the transformed space. Wait times average under 5 minutes for all customers. Loan preapprovals are now processed through blind evaluation protocols.
No names or photos attached to initial reviews. We’ve increased community lending by 63% while actually decreasing default rates. They moved to her office, formerly Weber’s space, now decorated with community achievement awards and financial education materials. The numbers tell a compelling story. Coleman notes.
But how does it feel on the ground? Diane considers thoughtfully. There was resistance initially. Habits formed over decades don’t change overnight. But success is persuasive. When people see better results from more equitable practices, opposition fades. Later that afternoon, Coleman meets Sarah Chen at Pinnacle headquarters. Now a recognized industry leader in banking equity, Chen presents the comprehensive metrics from the first year of reforms.
Discrimination complaints down 87%. Minority business loans up 64%. Employee satisfaction at record highs. And most significantly for the skeptics, overall profitability increased 12%. She closes her presentation tablet. The business case has been conclusively made. And the human case? Coleman asks. Chen smiles.
That’s evident in the stories we hear daily. The first generation college student who secured financing. The immigrant family approved for their first mortgage. the minorityowned business that expanded with proper capital access. Banking isn’t just about money, it’s about opportunity. As they conclude their meeting, Chen mentions, “You might be interested to know that Thomas Weber completed the antibbias certification program.
He’s been volunteering teaching financial literacy in Southside Community Centers.” Coleman nods thoughtfully. “People can change when properly motivated.” Later that evening, while leaving a downtown restaurant, Coleman encounters Weber unexpectedly. There’s a moment of tension as they recognize each other.
Both men recalling their confrontation a year earlier. Weber looks different, humbler, his expression more open. He wears no banker’s armor of expensive suit and institutional authority. Dr. Coleman, he acknowledges with a slight nod. Mr. Weber, Coleman returns evenly. I’m working with the Urban Financial Literacy Project now, Weber offers after an awkward pause.
Teaching budgeting and credit building in communities I previously underserved. Coleman studies him, finding it rewarding. Challenging, Weber admits. Confronting my biases daily isn’t comfortable, but necessary. He hesitates, then adds, “I’ll never fully understand the damage I caused throughout my career, but I’m trying to balance the scales in what time I have left.
” Their interaction remains brief, not friendship, but acknowledgement of growth and change. As they part ways, Coleman reflects that the most surprising outcome wasn’t Vber’s downfall or his own increased influence, but how addressing systemic problems ultimately benefited everyone involved. the bank, its employees, its customers, and even Weber himself finally forced to confront the biases that had limited his own humanity.
In the final scene, Coleman meets with a group of young minority entrepreneurs who previously couldn’t secure bank financing despite solid business plans. He listens to their stories of doors closed, opportunities denied, potential stifled before connecting them with Pinnacle’s new inclusive lending program.
The system is far from perfect, he tells them candidly. But for perhaps the first time, it’s genuinely evolving. Your success will further that evolution. As a young woman outlines her tech startup proposal, Coleman sees himself decades earlier, talented, determined, yet facing unnecessary barriers. The difference is that her path, while still challenging, won’t include the same systemic obstacles he faced.
The cycle of positive change continues. Each success creating space for the next generation. Your subscription helps us continue sharing these important stories with a wider audience. Hit the like button if you believe in standing up against discrimination and prejudice in all its forms. Share your own experiences in the comments below.
Have you ever been underestimated based on appearance? Did someone judge you before knowing your true value? The most compelling stories might inspire our future episodes. What happened today isn’t just a story, it’s a reminder. Silence protects systems, but courage rewrites them. At Beat Stories, we don’t just watch change, we document it.
Subscribe for more real stories that challenge power and amplify truth.