Bank Manager Wipes His Shoe on Black Woman’s $10M Check—Then the Bank Fires Him
The certified check was still in Martin Heller’s hand when Alicia Grant turned the verification screen toward him.
“First Continental is the issuing bank. I can authenticate it from here.”
Martin did not touch the keyboard. I was standing beside Marion Caldwell Price with the commercial onboarding packet open against the counter. The placement instructions listed Southline Community Capital, the community lending fund, and the $10 million deposit we had scheduled for that morning. I had confirmed the appointment two business days earlier. Nothing in the packet was incomplete. Marion had already provided her identification and corporate documents. Alicia had entered the information without difficulty. The normal next step was issuing bank verification.
Instead, Martin looked at Marion again. He had come out of his office after Alicia notified him of the deposit size. Since then, most of his questions had been about Marion rather than the check. How long had the company existed? Why was she opening the account at that branch? Why was a transaction that large being handled in person? Each answer was already somewhere in the documents in front of him.
Marion finally pointed toward the check.
“Is there a problem with the instrument?”
Martin held it beneath the lobby lights.
“I’m evaluating the entire presentation.”
I looked up from the packet. That phrase was the one that stuck with me. Not signature, not certification, not issuer—presentation. Alicia kept the verification window open. There was no fraud warning on her screen and no rejection from First Continental because nobody had contacted First Continental yet.
Martin asked for another source of funds explanation. Marion gave him the same answer contained in the placement letter. Southline was funding a lending pool for small businesses, affordable housing projects, and neighborhood health services. The account was supposed to keep part of that capital in the same area where the projects would operate.
Martin glanced at her linen jacket, then at the check again.
“I’ve seen people walk in here with paperwork that looks impressive.”
Alicia’s hands stopped above the keyboard. Marion did not answer the implication. She asked him to authenticate the check. Martin said he would decide what verification was appropriate.
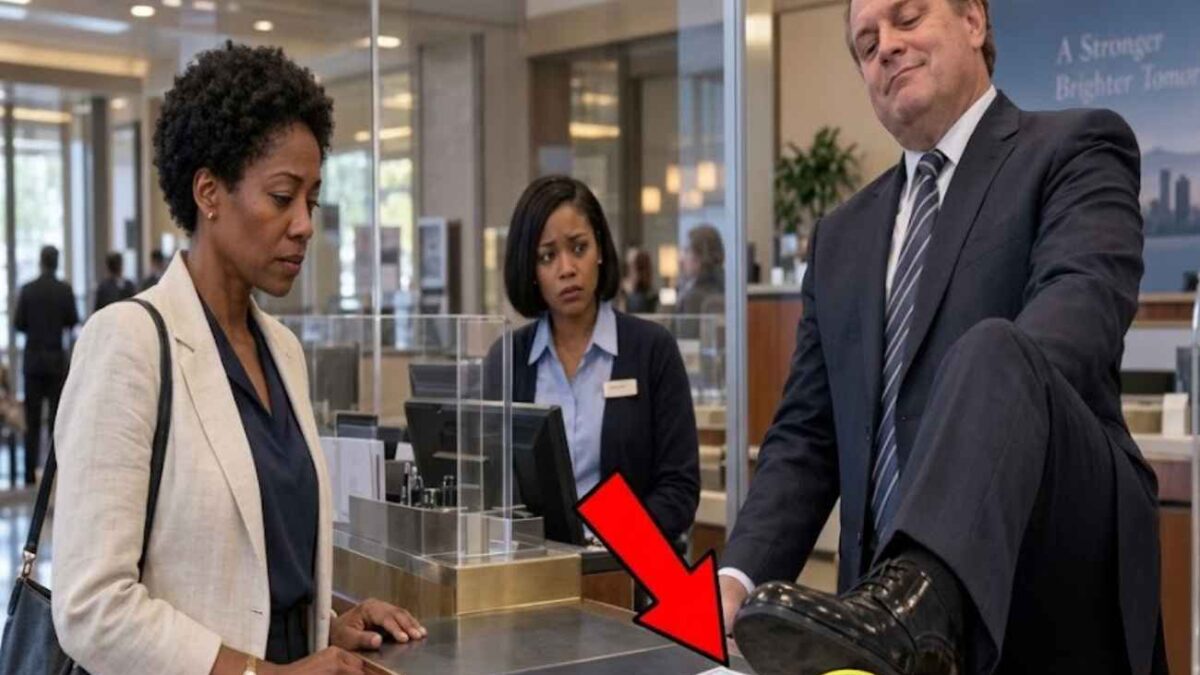
Then he lifted one foot against the lower rail of the counter. I saw the movement. I didn’t understand it. He dragged the bottom of his shoe across the face of the certified check once. The paper bent slightly under the pressure. A dark mark crossed the lower corner. Then Martin looked directly at Marion. He used a racial slur so explicit that Alicia stepped back from her terminal. Nobody needed him to explain what he meant.
Marion reached across the counter and took the check from his hand. She examined the mark. Then she placed the instrument inside the clear sleeve I had brought with the closing documents.
“Are you accepting the deposit?”
Martin straightened his jacket.
“I’m referring this for fraud review.”
“What fact triggered the referral?”
He did not name one. Instead, he said the branch could retain the check while the review was pending. Marion looked at me. I already had the custody section of the deposit packet open.
“If the bank is keeping the original,” I said, “we need a receipt identifying the instrument and the reason for retention.”
Martin told us that was unnecessary because the transaction had not been accepted. That closed the only route for the check to leave Marion’s hands. She placed the sleeve inside her portfolio.
“Then give me the branch decision in writing.”
Martin’s face tightened. He called toward the security desk. Noah Briggs approached from the lobby entrance. Martin told him we were refusing a fraud review and needed to be removed.
Noah looked at Marion, then at the counter.
“Is there a safety issue?”
Martin said it was a fraud matter. Noah did not move closer.
“That’s not what I asked.”
It was the only challenge he made. He had no authority to authenticate the check. He didn’t pretend he did.
Martin returned to Alicia’s terminal. He instructed her to close the teller side of the transaction as customer declined verification.
Alicia looked at the screen.
“She asked us to verify it.”
Martin repeated the instruction. She simply left the customer disposition field unchanged.
Martin moved around the counter and entered something under his own credentials. A new status appeared beside Marion’s transaction: Manual risk review.
Marion read it once. Then she closed her portfolio.
“We’re done here.”
She did not ask for the bank president. She did not tell Martin what Southline managed or what the deposit could mean to his branch. We walked out with the check.
In the parking lot, I called First Continental from the number already printed in our placement file and began documenting the branch disposition. Behind us, Martin’s referral had already left the counter. It was now part of the bank’s system.
First Continental confirmed the check before we reached Southline’s office. The verification officer matched the certification number, issue date, amount, and beneficiary information. He also confirmed something more useful: Heritage National had never contacted them.
I entered the confirmation into our transaction file and stopped there. The check was valid. We did not need three more records proving the same thing. The harder problem was what Heritage had already done with the transaction. Marion could not leave $10 million waiting while the dispute moved through another institution. The community fund had scheduled commitments coming due, including two small business lending pools and an early stage clinic project. By that afternoon, our treasury team had placed the money temporarily with an existing custodian. The projects stayed alive. The original Heritage placement did not.
The bank sent its preliminary response the next morning. I read it at my desk. According to Heritage, the branch had initiated heightened review of an atypical transaction. The customer then chose not to complete the verification process and remove the instrument before review could be concluded. The racial insult was addressed separately as alleged employee misconduct. That wording divided one event into two pieces. Martin’s behavior became a personnel concern. The fraud referral became ordinary risk management.
I sent Marion the response. She called me less than a minute later.
“They’re saying I stopped verification.”
“They are.”
“Keep the issuing bank confirmation with the complaint.”
That was all she asked. We filed the formal complaint that afternoon.
Two days later, Alicia Grant contacted our outside counsel through the number on the incident notice. She did not send internal bank records. She gave a factual statement about what she had personally handled. Her teller screen had shown no instrument alert before Martin intervened. Marion had provided the documents requested. Alicia had prepared to authenticate the check. Martin stopped that process and later instructed her to close the transaction as customer declined verification. She had refused to enter that description.
The next line in Alicia’s statement raised the stakes. Her customer-facing access had been suspended pending an internal conduct review. She was still employed. She was no longer working the counter. That gave the complaint a second consequence stemming from the same original decision. The bank was no longer dealing only with a disputed customer transaction. It was now reviewing the employee who would not make the record agree with management’s version.
Rachel Donnelly entered the case through the Federal Fair Banking Review channel. I met her for the first time in a conference room at Southline. She did not ask Marion to repeat Martin’s insult. She already had the written account. Her first question concerned the referral:
“What objective condition existed before the manual risk review was opened?”
We gave her everything Southline controlled: the onboarding packet, the check information, First Continental’s confirmation, the branch disposition. Alicia’s statement went through counsel separately. Heritage had to answer the rest.
Several days later, Rachel requested a meeting after the bank produced its regional risk guidance. I read the relevant page once. Branch managers were permitted to apply heightened review when transaction characteristics or client presentation created an atypical risk profile. There was no definition beside client presentation. No document type, no transaction threshold, no observable condition—just discretion.
Rachel asked whether we had ever seen the phrase before. We had not. Then she showed us the name attached to an older internal compliance submission: Caroline Mays. Caroline had worked in regional compliance before leaving Heritage nearly two years earlier. Her report had examined manual fraud referral across comparable commercial transactions. It did not claim every referral was improper. It compared similar transaction bands, account documentation, and product types. The difference appeared in who was selected for additional review. Black and Latino customers were being referred at materially higher rates, even when transaction characteristics and documentation were comparable. Caroline had identified the undefined presentation criterion as a control weakness. Her report had been acknowledged. The rule remained.
For the first time, Marion leaned back from the table. The check had already been proven valid. Now we knew the question was larger than whether Martin had disliked the way she looked. Her treatment fit a decision category the bank had already been warned could produce unequal scrutiny.
Heritage responded that branch managers needed discretion to prevent fraud. They also said Martin had historically been rated well for loss prevention. That defense did not remove the problem. It connected his judgment to the system that rewarded it.
Rachel expanded the production request—not to every complaint Heritage had ever received, only to manual referrals using the same presentation-based discretion, the prior findings tied to those referrals, Alicia’s employment action, and the approval history behind the regional guidance. Until then, Heritage had controlled the language used to describe what happened. That ended with Rachel’s request. The branch could still defend its decision. It could no longer define the question.
Rachel Donnelly’s final findings began with one question: what fact existed before Martin Heller opened the manual risk review? Heritage National had produced the transaction file, the regional guidance, Martin’s branch notes, prior complaint summaries, and the earlier compliance work completed by Caroline Mays. None of those records identified a defect in Marion Caldwell Price’s check. There had been no issuer warning, no identity mismatch, no document problem, no unusual account history because the commercial account had not even been opened yet. The only discretionary factor Martin had cited before stopping Alicia Grant’s verification process was the way the customer and transaction presented.
Rachel did not treat that language as proof by itself. She compared it with the records that followed. Caroline’s earlier review had already found that Black and Latino commercial customers were being selected for manual fraud review at higher rates than comparable customers with similar transaction sizes and documentation. Heritage had acknowledged that report. It had not removed the presentation criterion. It had not defined an objective threshold for using it. Managers were still allowed to turn an impression into a formal review state. Martin had done exactly that. His racial insult and what he did to the check were handled as individual misconduct. They made his judgment easier to understand, but Rachel’s finding did not depend on them. The procedural failure happened earlier. He had created suspicion before the bank had identified anything suspicious about the transaction.
Heritage tried one final distinction. Its counsel argued that Martin had authority to refer unusual transactions. They also said branch discretion was necessary in fraud prevention. Rachel agreed with the first half. Then she asked what made Marion’s transaction unusual before the referral. Nobody supplied a transaction-based answer. That ended the argument.
Martin’s employment was terminated after the bank completed its personnel process. The finding against him cited the racial abuse, misuse of fraud review authority, inaccurate description of Marion’s conduct, and his attempt to have Alicia record the transaction as a customer refusal.
Alicia’s case was handled separately. She had not approved the deposit. She had not challenged Martin’s managerial authority at the counter. She had simply refused to enter a fact she had not observed. Her customer-facing access was restored, and Heritage paid the wages she had lost during the internal suspension. There was no promotion attached to it. Her original teller entry remained in the file. That mattered more.
The regional problem produced a different consequence. Heritage withdrew client presentation from its fraud selection guidance. Future manual referrals required a documented transaction, identity, account, or instrument condition that another reviewer could actually identify. The bank also accepted independent monitoring of comparable referral outcomes under the regulatory resolution. That change was not added because one manager had behaved badly. It was required because the bank had already been warned that an undefined appearance-based factor was producing unequal scrutiny and had allowed the rule to remain active. Several older complaints tied to the same mechanism were reopened. Rachel did not tell us that every complaint would be sustained. She said they would be reviewed under the standard that should have existed when they were filed.
Marion’s own record was corrected first. The manual fraud referral was removed. The final disposition stated that Southline Community Capital had presented a valid certified instrument. It withdrew the proposed placement after improper branch handling. It did not say Marion refused verification. It did not say the check failed review. Those facts were now separate from Martin’s version.
Heritage later paid a regulatory penalty and entered a formal remediation agreement covering the referral process and complaint handling.
Marion did not return with the check. By then, Southline had completed due diligence on three community banks with existing small business and neighborhood development programs. The $10 million placement was divided among them. The broader community trust moved forward under Ruth Caldwell’s name.
A few months later, I was reviewing the first construction draw for one of the projects the fund had been created to support. An old pharmacy storefront was being converted into a neighborhood clinic. The contractor had finished the electrical work and was installing examination room cabinets when Marion arrived for the site review. She checked the milestone sheet. She asked one question about the completion date and signed the release authorization. Nobody there knew what had happened at Heritage National. They did not need to. The money had finally reached the work it was supposed to fund.
This story is fictional.